Financing a Wisconsin lake house: second-home mortgages from the Fox Valley to the Northwoods
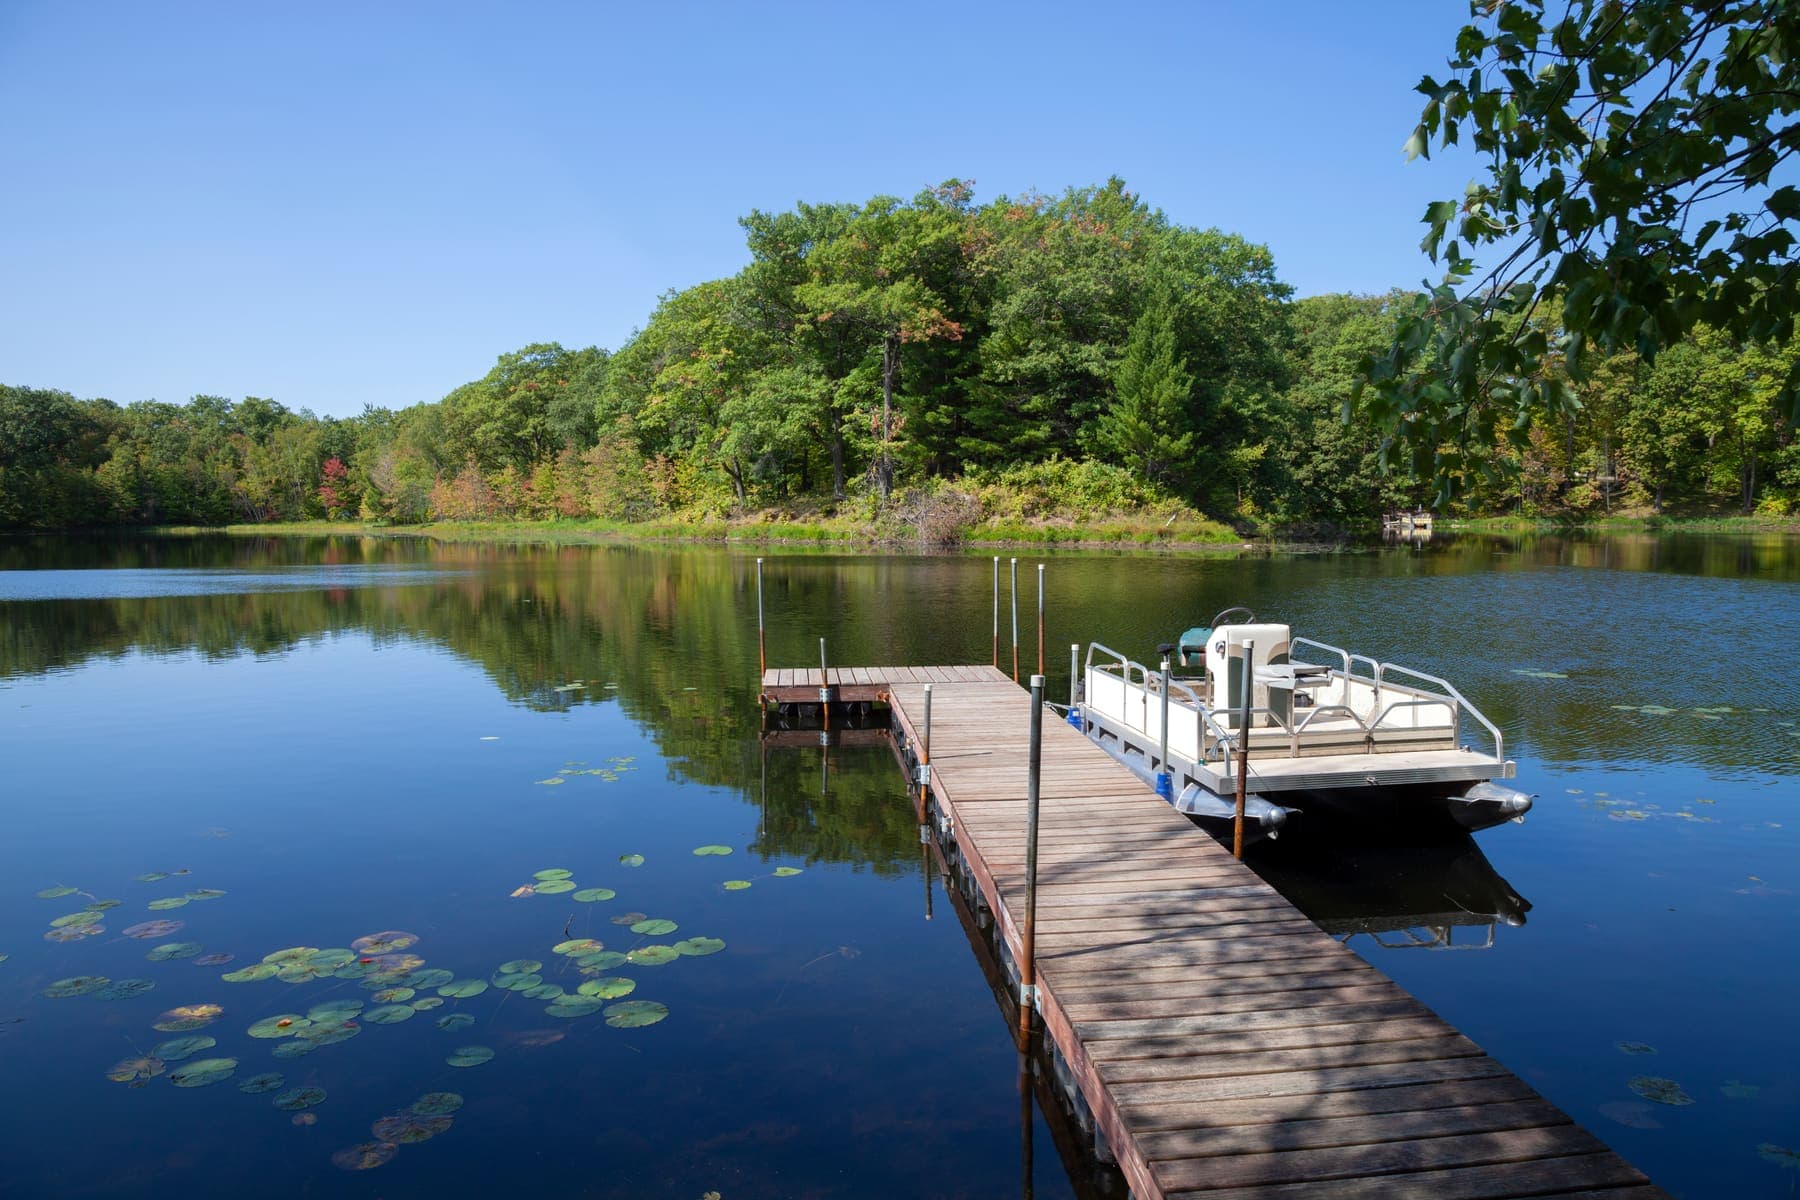
Half the families in the Fox Valley and a good share of northern Illinois have the same plan: a place on the water. Whether it's a cottage on Lake Winnebago, a cabin near Minocqua, or a year-round home on Green Lake, a second-home mortgage is different from the one on your primary residence. Here is what the rules are, what they cost, and where a lake property needs a lender who can use judgment.
 Home State Bank mortgage teamCrystal Lake, IL · Appleton, WI · NMLS 478452Updated September 9, 20267-minute read
What counts as a second home
Fannie Mae's definition, which most lenders use: a one-unit property you occupy for some part of the year, suitable for year-round use, that you control exclusively and that isn't subject to a rental or timeshare agreement. You can rent it out part of the year, and many lake owners do, but the rental income can't be used to qualify and you can't hand control to a management company. If you never plan to stay there, it's an investment property, with different rules and pricing.
Down payment, rates, and the pricing adjustment
Second homes need at least 10% down on a conventional loan. Rates run higher than a primary residence because of loan-level price adjustments the agencies charge: for 2026, between 1.125% and 4.125% of the loan amount depending on how much you put down, with the steepest adjustment above 80% loan-to-value. In practice that means a second home at 10% down can price a half point or more above the same loan on a primary residence, while 25% down closes most of the gap.
This is one place a portfolio lender changes the math. Home State Bank holds many second-home loans on its own balance sheet, so we don't pay the agency adjustment and don't pass it on. On the right file our portfolio second-home pricing has been below the agency rate at the same down payment.
| Loan-to-value | Adjustment (% of loan amount) |
|---|---|
| 60% or less | 1.125% |
| 60.01–70% | 1.625% |
| 70.01–75% | 2.125% |
| 75.01–80% | 3.375% |
| Above 80% | 4.125% |
Where lake properties trip agency underwriting
Lake homes are unusual by design, and unusual is what agency rules dislike. The issues we see most:
- Seasonal cottages without year-round heat or water, which fail the year-round-use test
- Shared wells, private roads, and easement access that need extra documentation
- Appraisals with few true comparables, because no two lake lots are alike
- Leased land and boat-slip arrangements
- Older homes with additions built before permits were routine
Taxes, insurance, and the carrying cost
Wisconsin's effective property tax rates are lower than Illinois, but lake frontage is assessed on land value and can run high; ask the seller for the last two bills. The Lottery and Gaming Credit applies only to your primary residence, so it won't reduce a second-home bill. Insurance on a lake property may need flood coverage even outside a mapped zone if the home sits near the water line, and seasonal properties sometimes need a policy that covers vacancy. Budget those before you fall in love with the view.
Illinois buyers, Wisconsin property
A large share of Wisconsin lake buyers live in McHenry County or the northern Chicago suburbs. That's fine: the loan is underwritten in Crystal Lake, and our Appleton office knows the Fox Valley and Northwoods markets, title companies, and appraisers. One lender, both sides of the line.
Questions people ask
- How much down do I need for a lake house?
- At least 10% on a conventional second-home loan. Putting 20% to 25% down significantly reduces the agency pricing adjustment, or a portfolio loan can avoid it.
- Can I rent my lake house on weekends?
- Yes, part-year rental is allowed on a second-home loan, but the income can't be used to qualify and a management company can't control occupancy. Full-time rental makes it an investment property.
- Can I use a HELOC on my primary home for the down payment?
- Yes, and it's common. A HELOC on your McHenry County or Fox Valley home can fund the down payment on the lake property; we count the HELOC payment in your ratios.
Sources
This article is general information, not financial, tax, or legal advice, and not a commitment to lend. Program terms, limits, and rates change; confirm current figures with a loan officer. Home State Bank, N.A. NMLS 478452. Member FDIC · Equal Housing Lender.